Winning a bigger storm payout does not mean your insurer has to pay your lawyer. Honestly, that's the sharpest takeaway from Florida's Sixth District Court of Appeal in October 2026, when judges shut down a bid for attorney fees by Hurricane Ian homeowners Susan Reed and Kent Lonngren against Citizens Property Insurance Corporation.
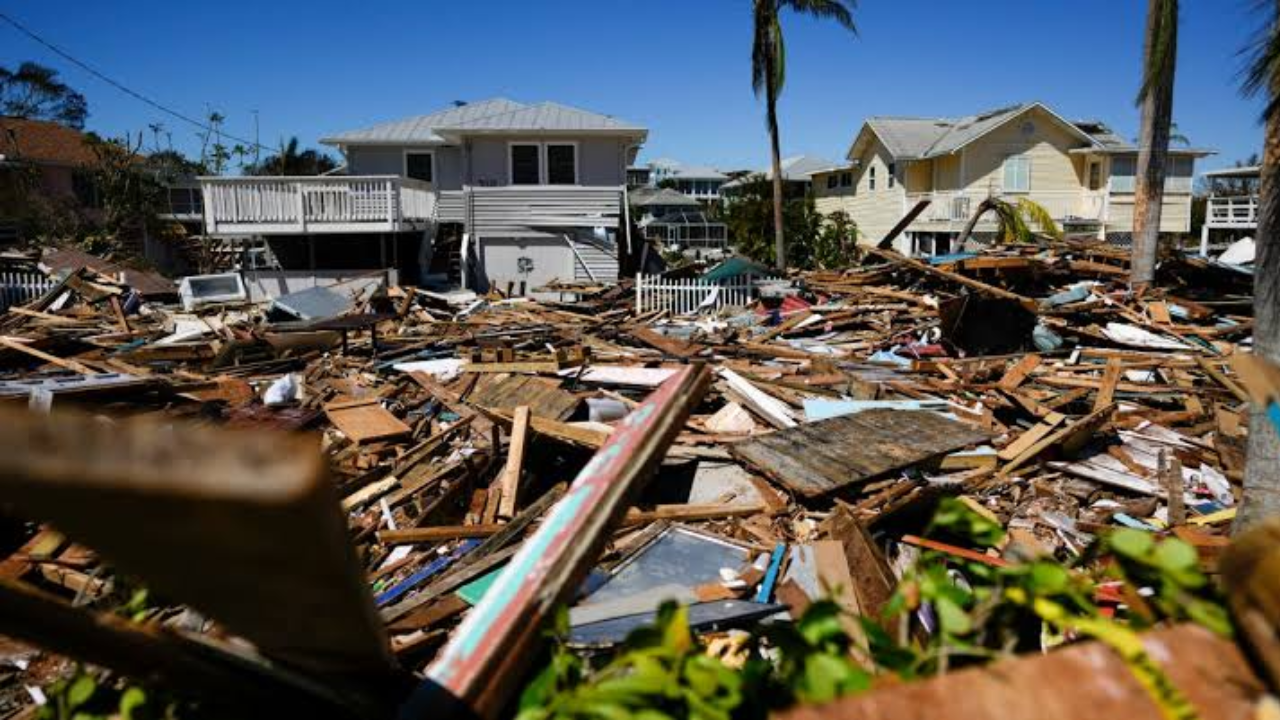
Picture the gap between what the insurer first offered and what repairs actually cost. Citizens accepted coverage after the October 2022 storm and issued an initial payment of $11,101.19, while the homeowners' estimate for repairs reached $157,727.00. After additional interim payments, the dispute moved into the policy's appraisal process, the homeowners filed suit before appraisal wrapped up, an appraisal award came back in their favor, and Citizens paid within the contract's 60-day window. When the homeowners pointed to that post-suit payment and claimed a "confession of judgment" entitled them to attorney fees, the appellate court said no.
That ruling—following a nearly identical Sixth District decision earlier that same month in Letteri v. Safepoint Insurance Co.—pulls back the curtain on a trap that catches plenty of policyholders off guard. A higher appraisal number feels like a victory. Yet when an insurer honors appraisal and pays on time, filing a lawsuit mid-stream usually won't turn the insurer into the payer of your legal bill.
How the Dispute Unfolded After Hurricane Ian
Storm claims rarely stall over a single number overnight. They tend to snowball as contractors inspect hidden water intrusion, roof decking issues, and code upgrades while insurers adjust in stages.
In Reed v. Citizens Property Insurance Corporation (decided October 16, 2026), the homeowners reported Hurricane Ian damage on October 4, 2022. Citizens accepted coverage and sent an initial $11,101.19 payment, followed by interim payments, with the final interim payment issued on June 1, 2023. Eight days later, the homeowners served a formal pre-suit notice.
Citizens responded by invoking the policy's appraisal clause to settle the dollar amount of the loss. Disagreements over selecting a neutral umpire slowed things down, and on September 26, 2023, the homeowners filed a lawsuit. The trial court put the litigation on hold while the umpire selection moved forward. Once the appraisal process concluded with an award favoring the homeowners, Citizens paid within the 60-day deadline set by the policy.
The homeowners argued that Citizens' payment after the lawsuit was filed operated as a confession of judgment, entitling them to attorney fees and prejudgment interest. Both the trial court and the Sixth District disagreed, affirming summary judgment for Citizens.
Why the Confession of Judgment Doctrine Fell Short
To understand why the court rejected the fee claim, you have to look at what Florida's confession of judgment doctrine actually exists to stop. Historically, courts used the doctrine when an insurer wrongfully denied coverage or forced a policyholder into court to get paid, and then caved by paying after litigation began. Without that rule, an insurer could stonewall until a homeowner hired a lawyer and sued, then pay the claim to dodge fee liability.
Here, the Sixth District saw a very different picture. There was no breakdown in the claims adjusting process that forced the homeowners to sue. Citizens accepted coverage, participated in the contractual appraisal mechanism, and paid the resulting award on time.
In Letteri v. Safepoint Insurance Co. (decided October 2, 2026), the Sixth District laid out the same principle on another Hurricane Ian claim involving a policy-limits appraisal payout of roughly $200,000. In Letteri, Safepoint accepted coverage, elected appraisal, and paid within the policy timeframe after the umpire issued the award. Suing while appraisal was underway didn't act as a necessary catalyst to force payment, so the confession of judgment doctrine didn't kick in.
The 90-Day Window Is Not an Appraisal Deadline
A common point of confusion among policyholders—and even some aggressive litigation strategies—involves Florida's pre-suit notice statute, section 627.70152. Under section 627.70152(4)(b), a policyholder may file suit if an appraisal or alternative dispute resolution hasn't concluded within 90 days after the expiration of the 10-day notice-of-intent period.
The Sixth District made clear what that rule does and doesn't do. It gives a homeowner permission to file a lawsuit once that clock passes. It does not impose a hard deadline forcing the appraisal itself to finish by day 90, nor does it automatically create a right to attorney fees if you sue before the appraisal wraps up.
Busy post-catastrophe calendars make that distinction huge. After a major hurricane like Ian, qualified appraisers and neutral umpires get swamped with hundreds of files across multiple counties. Delays caused by scheduling or umpire selection aren't the same thing as an insurer refusing to honor its policy.
Appraisal Rules and Policy Timelines Matter More Than You Think
When a claim goes to appraisal, the contract itself sets the ground rules for how the valuation moves forward and when money changes hands. Under the Citizens policy at issue in Reed, each side had 20 days after an appraisal demand to name a competent appraiser, and if the appraisers couldn't agree on a neutral umpire within 15 days, either side could ask a circuit judge to appoint one. Agreement by any two of the three—the two appraisers and the umpire—sets the binding amount of loss.
Equally critical is the post-award payment clock. Policies typically spell out a specific number of days—60 days in the Reed and Letteri disputes—for the insurer to pay an appraisal award once it's set. Hitting that deadline kept the insurer in compliance with the contract and undercut the argument that litigation was needed to pry loose the funds.
Where Policyholders Still Win Big
It's easy to read these appellate opinions and assume homeowners have no leverage left. That's not true. The Sixth District's rulings turn on specific facts: coverage was accepted, appraisal proceeded, and the award was paid on time.
Contrast that with disputes where an insurer flatly denies coverage from day one, refuses to participate in good faith, or drags out payment past contractual deadlines. For example, in October 2026, a Broward County jury sided with a Florida couple in a Hurricane Ian trial after Citizens had denied the claim, resulting in a verdict that legal coverage around the case noted could cost the insurer more than $400,000 on a claim originally valued around $46,000. Appellate courts have also pushed back against insurers on other procedural fronts, such as requiring carriers to prove prejudice rather than simply assuming it on late-notice defenses when policy language calls for it.
In other words, timing and posture dictate everything. Fighting over whether a storm caused covered damage or whether a carrier breached its obligations looks very different from suing mid-appraisal over how much repairs cost when the insurer is already using the appraisal clause.
Practical Steps Before Suing Over a Stalled Appraisal
If you're staring at a gap between your contractor's repair estimate and your insurer's check, don't treat a lawsuit as an automatic fee-shifting lever. Kinda tempting when bills pile up, I know, yet rushing to court can leave you paying out of pocket for legal representation even when the final appraisal number goes your way.
- Read the appraisal and payment clauses line by line. Check the exact deadlines for naming appraisers, picking an umpire, and paying an award after it's issued, as reported in coverage of the Sixth District's October 2026 rulings.
- Document every delay in writing. Keep a clear timeline of appraiser appointments, umpire proposals, inspection dates, and any pushback from the insurer so you know whether a delay stems from storm backlogs or actual foot-dragging.
- Ask your attorney directly about fee exposure. Before filing suit while an appraisal is pending, get a straight answer on how fees are handled if the insurer pays the award on time—never assume a favorable appraisal award guarantees fee recovery.
- Track post-award payment deadlines closely. Once an appraisal award is entered, mark the contractual payment date on your calendar and verify whether the carrier pays in full before that window closes.