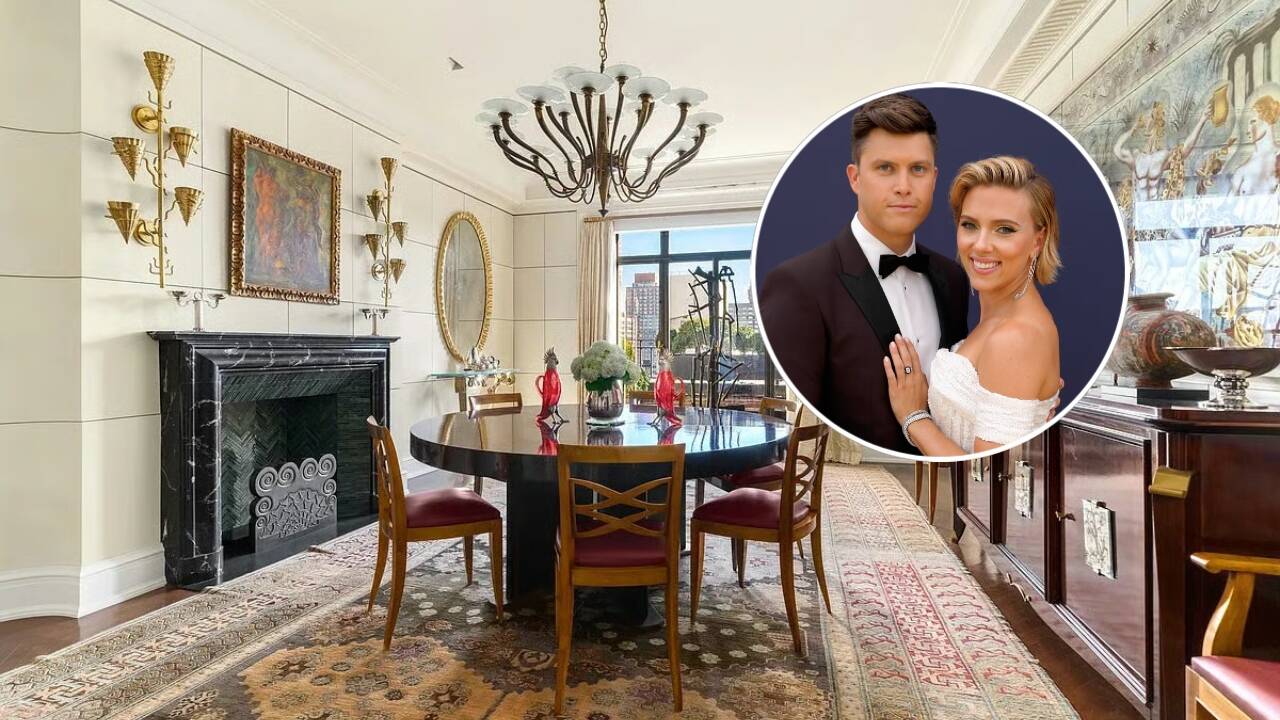
A 52.7% discount off an initial asking price in Manhattan’s ultra-prime residential market is neither a miracle of celebrity negotiation nor a statistical anomaly. When a penthouse originally listed at $27.5 million closes at $13 million, the transaction exposes a structural breakdown in asset pricing, liquidity constraints at the top of the luxury curve, and the severe carrying-cost penalties embedded in New York City real estate. To understand how a $14.5 million nominal value destruction occurs on a single residential asset, one must strip away the celebrity narrative and analyze the transaction through the mechanics of illiquid market microstructure, anchoring bias, and seller capitulation.
The Architecture of Price Discovery Failure
In liquid financial markets, price discovery happens continuously through tight bid-ask spreads and high transaction volume. Ultra-prime real estate—defined in Manhattan as properties priced above $10 million—operates under the exact opposite conditions. The asset class is characterized by extreme heterogeneity, thin order books, and high transaction friction.
When a seller lists a penthouse at $27.5 million, that figure rarely reflects a discounted cash flow model or a rigorous comparable-sales regression. Instead, it represents an aspirational anchor set during a period of peak market exuberance or constructed to leave room for perceived negotiation. In behavioral economics, anchoring bias dictates that initial price points disproportionately influence subsequent valuations. However, in ultra-prime real estate, an excessively high initial anchor acts as a toxic signal to institutional-grade buyers and their family offices.
Sophisticated buyers in the eight-figure bracket do not evaluate properties on emotional appeal alone; they evaluate price per square foot, capital expenditure requirements, monthly common charges, and real estate tax liabilities. When an asking price sits 40% to 50% above clearing-market comparables, the property fails to generate competitive bidding during its critical initial 60-day listing window. Once a trophy asset crosses the 180-day mark on the market without an accepted offer, it acquires market stigma. Buyers assume either a hidden structural defect, an intractable co-op board, or an irrational seller. At that juncture, price discovery stalls entirely, and the bid-ask spread widens into an unbridgeable chasm.
The Carrying Cost Function and Seller Capitulation
The primary driver forcing a $27.5 million ask down to a $13 million close is the relentless mathematics of holding costs. Unlike an unleveraged equity position that costs nothing to hold during a drawdown, a Manhattan penthouse bleeds cash every month it remains unsold.
The holding cost function for an ultra-prime Manhattan residence consists of four primary variables:
- Property Taxes: Following New York State’s elimination of the SALT (State and Local Tax) deduction cap utility for high earners, annual property taxes on an eight-figure condo frequently exceed $100,000 to $200,000 per year, paid out of post-tax dollars.
- Common Charges or Maintenance Fees: Full-service luxury buildings with extensive amenity packages, high staff-to-unit ratios, and substantial insurance premiums regularly assess $8,000 to $15,000+ per month in non-deductible operating fees.
- Opportunity Cost of Capital: Even if the seller owns the asset free and clear of debt, $13 million to $20 million in trapped equity carries a massive opportunity cost. In an environment where risk-free Treasury yields hover between 4% and 5%, tying up $15 million in an illiquid, non-yielding residential asset costs the owner $600,000 to $750,000 annually in foregone risk-free return.
- Physical Depreciation and Renovation Obsolescence: Ultra-prime buyers demand turnkey perfection. A penthouse styled ten years ago requires a gut renovation costing $800 to $1,500 per square foot. Every year the property sits unsold, its interior finishes depreciate further against newly constructed supertall developments on Billionaires' Row or Hudson Yards.
When you sum direct cash outflows (taxes and maintenance) with the opportunity cost of trapped equity, a seller holding a stagnant $20+ million listing easily absorbs $1 million to $1.5 million in annual economic drag. Over a multi-year marketing cycle, these cumulative losses erode the seller's psychological attachment to the original $27.5 million anchor. Capitulation occurs when the marginal pain of another year of carrying costs exceeds the utility of holding out for a theoretical higher bidder.
Separating Known Transaction Mechanics from Market Hypotheses
In analyzing high-profile celebrity acquisitions, rigorous discipline requires separating verified public-record data from structural market hypotheses.
Established Facts:
- The Spread: The delta between the peak asking price ($27.5 million) and the recorded closing price ($13 million) represents a 52.7% reduction.
- Transaction Friction: New York State and New York City impose progressive mansion taxes and transfer taxes on residential sales. For a $13 million transaction, the buyer absorbs a 3.25% New York State Mansion Tax ($422,500), alongside standard closing costs, title insurance, and legal fees. Had the property closed at $27.5 million, the Mansion Tax bracket would have jumped to 3.90% ($1,072,500).
- Market Tier Dynamics: Manhattan residential transactions above $10 million experienced significant repricing between peak cycle valuations (2014–2016) and subsequent post-pandemic interest rate adjustments, particularly for pre-war co-ops and non-new-development penthouses.
Educated Hypotheses Regarding the Discount:
- Renovation Capital Expenditure Offset: A discount exceeding 50% strongly indicates that the penthouse requires a comprehensive architectural overhaul. If a 4,000-to-5,000-square-foot penthouse requires $5 million to $7 million in construction costs and two years of architectural permitting to meet modern ultra-prime standards, the buyer deducts both the hard construction costs and a risk premium for time and execution hassle directly from the acquisition price.
- Co-op vs. Condo Liquidity Discount: If the asset is structured as a cooperative rather than a condominium, the buyer pool shrinks by roughly 70% to 80%. Co-ops restrict foreign buyers, LLC purchases, pied-à-terre usage, and high debt-to-income ratios. Co-op boards frequently reject celebrity buyers due to privacy and security concerns for other residents. Securing board approval as a high-profile public figure requires exceptional liquid post-closing asset verification, which simultaneously shrinks the pool of competing buyers and strengthens the approved buyer's negotiating position against a desperate seller.
- Estate or Divorce Liquidation: Deep discounts of this magnitude in Manhattan frequently correlate with non-economic forced sellers—specifically estate settlements where heirs prioritize immediate liquidity to pay estate taxes, or matrimonial dissolutions where court-mandated timelines override price maximization.
How Buyers Engineer Asymmetric Acquisitions
Acquiring a trophy asset at a 50%+ discount is not a passive event; it requires executing a disciplined acquisition protocol designed to exploit seller fatigue. Family offices and wealth managers representing ultra-high-net-worth individuals follow a repeatable sequence to capture these dislocations.
First, buyers filter out fresh inventory and target aged listings—specifically properties that have undergone at least two price reductions over 12 to 24 months. By tracking days on market (DOM) and historical listing price drops via brokerage databases, the buyer identifies sellers whose psychological anchoring has already been fractured.
Second, the buyer eliminates all contingencies that create execution risk for the seller. In Manhattan, cash offers without mortgage contingencies are the baseline requirement for deep-discount bidding. By demonstrating immediate liquidity—often via liquid brokerage statements showing post-closing reserves exceeding three to five times the purchase price—the buyer presents certainty of execution. To a fatigued seller bleeding $100,000 a month in carrying costs, a guaranteed 30-day cash close at $13 million holds higher risk-adjusted value than a speculative $16 million offer contingent on financing or complex board reviews.
Third, the buyer anchors the counter-offer not to the seller's asking price, but to replacement cost minus depreciation. The buyer's team presents a line-item construction budget detailing every outdated mechanical system, window replacement, and layout inefficiency. By framing the $13 million bid as the maximum mathematically viable entry point once $6 million in necessary renovations are factored in, the buyer shifts the negotiation from subjective taste to objective capital allocation.
The Limitations of Distressed Trophy Acquisition
While acquiring a $27.5 million-listed penthouse for $13 million appears to generate $14.5 million in instant paper equity, this strategy carries severe operational and financial traps that invalidate simplistic "bargain" narratives.
Illiquidity Cuts Both Ways: The exact market friction that allowed the buyer to acquire the property at a steep discount will apply when the buyer eventually attempts to exit. A niche penthouse with idiosyncratic layout constraints or strict building rules does not become instantly liquid simply because it was bought cheaply.
The Renovation Cost Overrun Trap: In Manhattan, residential construction costs are notoriously volatile. Landmark Preservation Commission approvals, strict building alteration agreements (which frequently limit construction to summer months or specific hours), and union labor requirements routinely push renovation budgets 25% to 40% over initial estimates. If a buyer acquires an unrenovated penthouse for $13 million and spends $8 million over three years renovating it—while paying carrying costs throughout the construction period—their all-in basis quickly climbs to $22 million. At that basis, the margin of safety against future market downturns narrows considerably.
Tax Assessment Revaluation Risk: While New York City property taxes do not automatically reset to the exact purchase price upon sale in the same manner as California’s Proposition 13, major building alterations and structural permits trigger Department of Finance reassessments. Significant capital improvements permanently elevate the property's annual tax baseline, permanently impairing its net yield and future resale appeal.
Tactical Playbook for High-Net-Worth Capital Allocation
For capital allocators, family offices, and principals evaluating ultra-prime residential real estate in supply-constrained urban cores, the $13 million penthouse transaction provides a clear operational blueprint:
- Abandon Asking-Price Multiples: Never benchmark an offer as a percentage discount off an initial listing price. A 50% discount off an arbitrary number is meaningless. Value the asset strictly on an all-in basis: Purchase Price + Closing Costs + Hard/Soft Renovation Costs + Construction-Period Carrying Costs. Compare that total basis against recently closed, fully renovated turnkey comparables within a four-block radius.
- Monetize Speed and Certainty: When bidding on stale inventory (365+ days on market), trade price for certainty. Offer all-cash terms, waive inspection contingencies after conducting pre-offer engineering walk-throughs, and provide complete financial disclosure packages upfront to neutralize seller anxiety.
- Target Structural Friction: Focus capital on assets penalized by temporary or solvable friction—such as dated interiors, poor staging, or estate-sale bottlenecks—while strictly avoiding permanent functional obsolescence, such as compromised light/air rights, noisy commercial ground-floor tenants, or underfunded building reserve accounts facing imminent capital assessments.
When ultra-prime markets enter periods of high interest rates and widening bid-ask spreads, sellers who refuse to mark their assets to market bear the full brunt of carrying-cost decay. Patient buyers who maintain liquid reserves and price assets based on all-in replacement costs—rather than seller nostalgia—will continue to capture massive downward price dislocations across Manhattan's top tier.