Standard reporting on the United Kingdom's approval of gas production at the North Sea Jackdaw field frames the decision as a binary moral collision between climate ambition and energy pragmatism. That framing misses the real structural tension: a political coalition elected on a pledge to halt new offshore hydrocarbon licenses is governing an aging basin through legacy permits, winter supply anxiety, and fiscal strain.
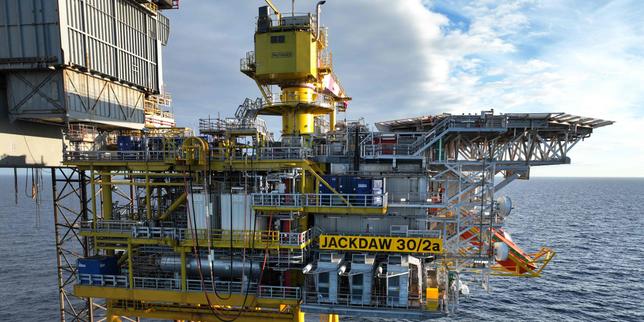
In late October 2026, Energy Secretary Miatta Fahnbulleh cleared the regulatory path for the North Sea Transition Authority to grant consent for gas production at Shell's Jackdaw field, alongside a £2 billion transition fund linked to North Sea revenues. First gas began flowing in mid-November 2026, arriving just as household energy bills faced sharp upward pressure and intra-party friction intensified over larger fields such as Rosebank. If you enjoyed this piece, you might want to read: this related article.
Conventional coverage treats this sequence as simple hypocrisy or simple necessity. A rigorous analysis requires separating legal license status from operational output, mapping how marginal domestic supply interacts with benchmark gas pricing, and isolating the fiscal and political trade-offs behind each claim.
Deconstructing the Competitor Narrative
Typical headlines built around the Jackdaw controversy rely on three recurring claims: For another look on this development, check out the recent coverage from NBC News.
- The manifesto contradiction claim: Critics argue that approving offshore gas extraction violates the Labour Party's pre-election commitment against new North Sea oil and gas licenses.
- The bill-relief shortcut: Supporters and critics alike often argue—or dispute—whether domestic North Sea gas directly lowers household heating bills.
- The jobs-versus-emissions ledger: Coverage frequently weighs short-term employment and winter supply against carbon budgets and climate credibility.
The first limitation of this framing is that it conflates new license issuance with consent to produce under pre-existing licenses. A ban on awarding new exploration or production licenses restricts future entry into the basin; a consent decision on an already licensed field governs whether capital already committed can move into active extraction. Treating those two regulatory gates as identical obscures where executive discretion actually operates.
This creates a second analytical gap: treating domestic production volume as a direct lever on retail tariffs. Natural gas in interconnected European and British markets is priced at the margin against international pipeline flows, liquefied natural gas cargoes, storage levels, and weather-driven demand. Adding domestic supply can alter import dependency and marginal supply balances without automatically depressing consumer bills in the way domestic-only price models imply.
The third blind spot is treating North Sea policy as a static choice rather than a multi-period transition problem. Declining legacy fields, shifting tax regimes, capital mobility among operators, and grid decarbonization timelines interact over years rather than single news cycles.
The Four Structural Variables of North Sea Gas Policy
To evaluate any North Sea gas decision without slogans, four variables must be examined separately.
- License Vintage and Consent Authority: Whether a project holds an existing license or requires a new award determines the legal and political baseline. Environmental consent and production sign-off operate on different timelines from initial licensing.
- Marginal Supply vs. Retail Price Transmission: Domestic gas output affects national supply share and import exposure, whereas retail prices reflect wholesale benchmarks, network charges, hedging structures, and demand elasticity. Ministers themselves have acknowledged that Jackdaw gas does not translate directly into lower household bills.
- Employment Concentration vs. Aggregate Job Creation: Offshore projects often preserve specialized technical roles and supply-chain activity in specific regions even when headline net job creation is modest. Confusing total national employment with localized skill retention distorts the labor argument.
- Fiscal Extraction vs. Capital Retention: Higher taxation on North Sea producers can generate public revenue or fund transition initiatives, yet heavy tax burdens alongside policy uncertainty can accelerate asset sales and capital reallocation toward other basins.
What Is Established vs. What Remains Contested
In assessing the Jackdaw decision and broader North Sea policy, several facts are established while key impacts remain contested or conditional.
Known facts include the government's October 2026 consent for Jackdaw gas production, the existence of prior licensing before Labour entered office, the start of initial gas flows in November 2026, the launch of a transition fund linked to North Sea proceeds, and explicit government acknowledgment that the field will not lower consumer energy bills. Ongoing basin exits and asset restructurings by operators citing tax and regulatory conditions are also observable market events.
By contrast, the net climate impact depends on lifecycle emissions, fugitive methane controls, UK carbon-budget accounting, and whether imported gas or higher-carbon alternatives would otherwise fill demand. Similarly, the long-run fiscal yield is an educated hypothesis contingent on future commodity prices, production decline curves, tax adjustments, and operator reinvestment decisions rather than a guaranteed cash stream.
Cause-and-Effect Chains Standard Coverage Misses
Domestic Gas, Winter Supply, and Household Bills
A common assumption in public debate is that turning on a domestic gas tap mechanically cuts winter heating bills. In practice, Britain participates in a traded gas market where prices are set by marginal supply and demand across interconnected pipelines and LNG terminals.
When domestic output rises from a field like Jackdaw, the immediate operational effect is higher indigenous supply availability during peak seasonal demand rather than a unilateral reset of wholesale clearing prices. Even if domestic production supplies a noticeable share of UK output at peak, retail bills depend on broader market pricing, supplier hedging, and policy costs.
This is why policy analysts separate energy security from bill affordability. Increasing domestic supply can reduce reliance on external suppliers during tight winters, while structural improvements in household energy efficiency—such as insulation and heat pumps—address baseline demand directly.
Labor Politics, Union Positions, and Coalition Strain
North Sea policy sits at a fault line inside the governing coalition and wider labor movement. Some unions have warned against abrupt phase-outs without clear replacement work, arguing that sudden restrictions risk stranding skilled offshore workers and coastal communities.
At the same time, climate-focused lawmakers and campaigners view approving fossil fuel extraction as a breach of environmental credibility, especially as debates widen toward larger developments like Rosebank. When a government attempts to hold both positions—no new licenses while permitting existing projects and funding clean energy—it faces pressure from both flanks simultaneously.
Ringfenced Transition Funds and Basin Capital Flight
Pairing hydrocarbon approval with a dedicated transition or energy wealth fund attempts to convert an extraction decision into clean-energy capitalization. Economically, that creates an internal cross-subsidy between a declining or contested incumbent sector and future low-carbon assets.
The operational risk lies in the tax-and-exit loop. If producers face elevated levies and shifting rules while decommissioning liabilities loom, some operators sell mature assets or redirect capital to basins with lower fiscal friction. Over time, shrinking capital expenditure narrows the very revenue base intended to finance transition spending.
Operational Framework for Evaluating Offshore Energy Decisions
Policymakers, energy executives, and institutional analysts evaluating contested offshore approvals can apply a five-step decision sequence before taking a position:
- Audit legal status first: Separate new license awards from consents on pre-existing licenses and environmental re-submissions.
- Trace price vs. volume effects: Distinguish between added physical supply during winter demand and actual transmission into consumer tariffs.
- Disaggregate labor claims: Separate newly created roles from retained or transferred specialized positions and regional supply-chain work.
- Test fiscal durability: Model how tax rates, decommissioning rules, and investment allowances affect operator retention versus asset divestment.
- Account for substitution and carbon leakage: Compare emissions and import profiles against alternative supply pathways rather than evaluating the project in isolation.
Every analytical framework has boundaries. Precise reservoir decline curves, forward commodity prices, and political vote counts inside parliament shift continuously, meaning no static matrix eliminates judgment. Even rigorous lifecycle and fiscal modeling cannot turn an inherently contested value trade-off—between near-term supply/fiscal pragmatism and strict climate alignment—into a purely technical calculation.
Strategic Recommendation
The most coherent path for UK energy governance is to decouple legacy-consent triage from a binding, transparent wind-down and workforce-transition schedule rather than relying on ad-hoc project approvals paired with rhetorical pledges. Ministers should publish clear statutory criteria governing existing licenses, ringfence a defined share of transition funding for regional skills conversion and industrial repurposing in affected coastal hubs, and pair supply decisions with enforceable demand-reduction and grid-readiness milestones. Doing so replaces reactive political firefighting with predictable rules that give workers, investors, and climate monitors a single verifiable standard to judge performance against.