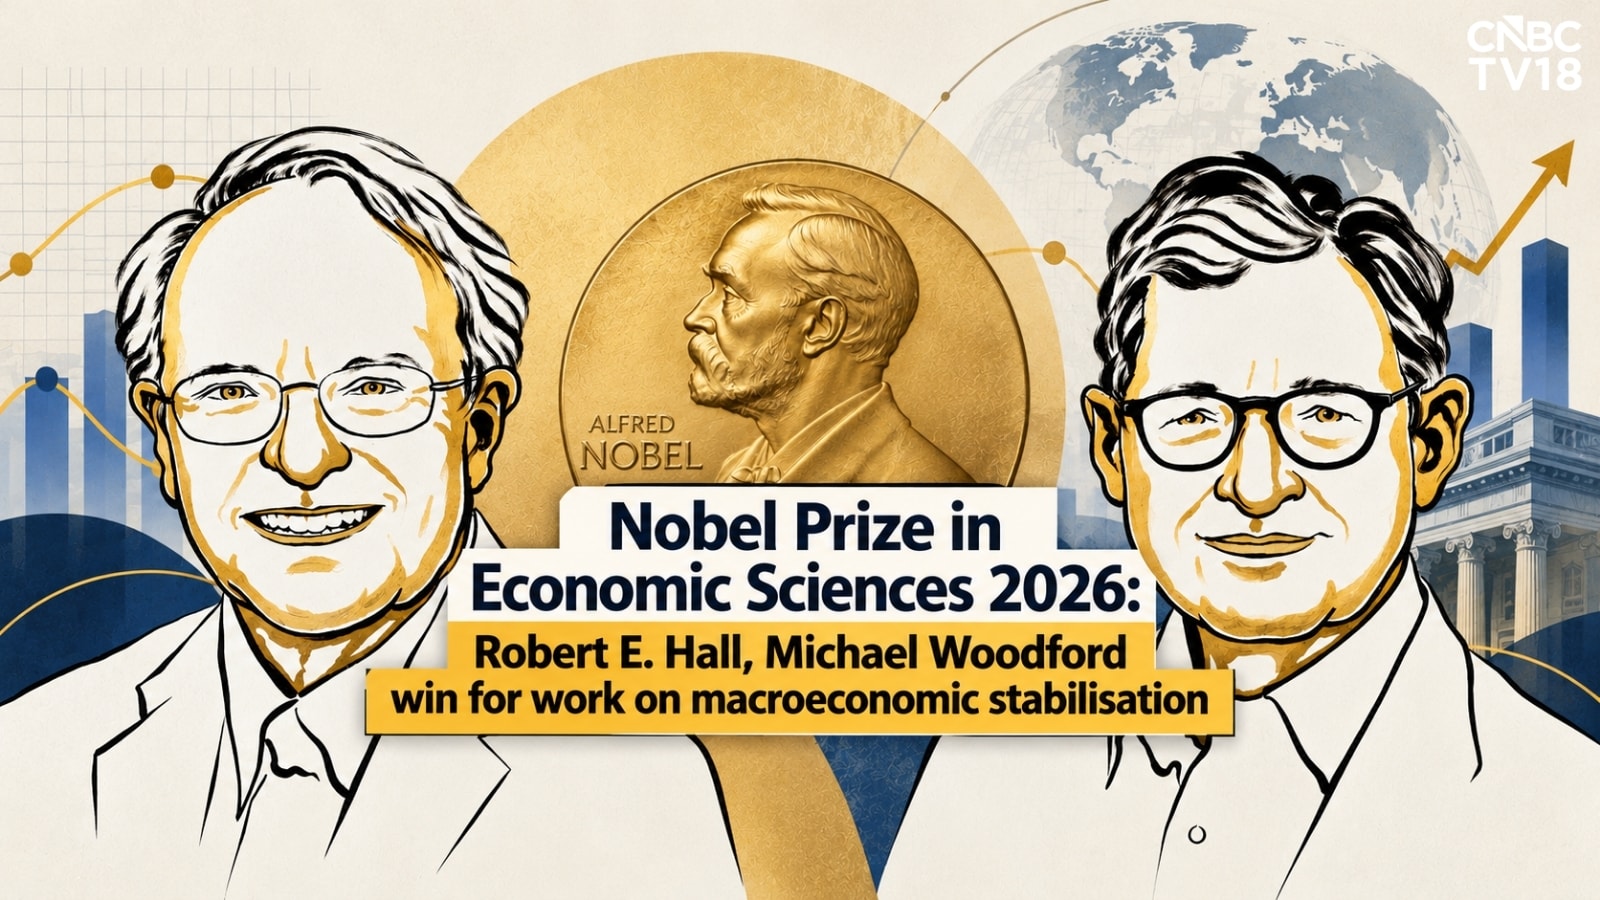
Standard macroeconomic headlines treat Nobel recognition as a prize for predicting the next quarter's interest rate, yet Robert E. Hall and Michael Woodford earned their stature in the discipline by exposing why markets fail to clear smoothly and why central bank expectations govern real economic output. Because no external competitor text or URL was supplied alongside the headline, this analysis reconstructs the core analytical pillars implied by a report on Hall and Woodford's Nobel-worthy economics, then rebuilds the subject around strict causal mechanisms, explicit empirical boundaries, and operational policy logic. Readers seeking a rigorous breakdown of labor market matching, sticky prices, forward guidance, and fiscal multipliers will find here a structured map of how frictions and expectations interact across business cycles.
The Structural Divide in Modern Macro Friction
Traditional frictionless equilibrium models assume wages and prices adjust instantaneously to equate supply and demand across every market. When empirical data shows persistent unemployment during recessions or sluggish inflation responses to monetary shifts, frictionless baselines fail to explain the persistence of real shocks. Hall and Woodford address this gap from two complementary angles: Hall's work centers heavily on real frictions in labor matching and business-cycle fluctuations, while Woodford's work centers on nominal rigidities, intertemporal optimization, and the design of monetary policy under forward-looking expectations.
To evaluate why an economy stalls rather than self-correcting overnight, analysts separate real frictions from nominal frictions. Real frictions alter the physical or institutional cost of reallocating resources—such as time and search effort required to match job seekers with vacancies, or capital adjustment costs. Nominal frictions operate through prices, wages, or contracts denominated in money that do not reset continuously, causing changes in nominal interest rates or money supply to affect real quantities like output and employment in the short run.
A known empirical fact in labor economics is that unemployment and job vacancies move in opposite directions over the business cycle, a relationship summarized by the Beveridge curve, while hiring rates and separation rates exhibit substantial gross flows even when net employment changes slowly. An educated hypothesis drawn from matching theory is that shifts in match productivity or separation rates alter the expected return to posting a vacancy, magnifying small productivity disturbances into large swings in unemployment—a mechanism debated intensively in the post-2000 literature on the Shimer puzzle, where standard search-and-matching calibrations struggled to match observed unemployment volatility without specific wage-stickiness or surplus-sharing assumptions.
Consider a regional manufacturing hub facing a sudden drop in export orders. Even if nominal wages are flexible downward, workers and firms do not instantly reassign themselves across tasks without search delays, retraining lags, and relocation costs. If firms simultaneously delay hiring because expected revenue per worker falls, job openings contract sharply while displaced workers spend longer searching, turning a demand shock into prolonged idle capacity.
Mechanics of Expectations and Nominal Rigidity
When prices and wages are sticky over short horizons, a central bank's control over a short-term nominal policy rate translates into control over the short-term real interest rate—roughly the nominal rate minus expected inflation—once inflation expectations are anchored or sluggish. In New Keynesian frameworks closely associated with Woodford's contributions, current inflation and current output depend not only on current conditions and past inertia, but heavily on households' and firms' expectations of future income, future interest rates, and future inflation.
This forward-looking structure creates both power and vulnerability for policymakers. Power arises because central banks can shape current economic activity by committing to future policy paths, often termed forward guidance, rather than relying solely on today's rate move. Vulnerability arises because announcements about future policy only move today's spending if economic agents believe the central bank will follow through when those future states arrive—a credibility and time-consistency challenge with roots stretching back to Kydland and Prescott.
The second limitation in standard expectations-driven models involves information and modeling assumptions. Rational expectations assume agents understand the structural model of the economy and form forecasts consistent with that model's true probability distribution. In practice, households, small businesses, and even professional forecasters operate with incomplete information, adaptive learning, or heterogeneous beliefs, which can dampen or distort the transmission of central bank communication.
To see how forward guidance operates in mechanism terms, suppose a central bank holds its policy rate near zero during a weak recovery and states it will keep rates low even after inflation begins to rise slightly. If firms believe borrowing costs will stay low longer than previously expected, their expected real discount rate falls across multiple periods, encouraging earlier capital investment and inventory restocking today. Conversely, if firms doubt the pledge—suspecting the central bank will hike rates as soon as inflation ticks up—current investment reacts far less.
Fiscal Multipliers and Zero-Lower-Bound Constraints
Standard textbook intuition often suggests that higher government spending crowds out private investment dollar for dollar through higher interest rates, yielding a fiscal multiplier below one. That crowding-out mechanism relies on a central bank responding to higher aggregate demand and rising inflation pressure by raising nominal and real interest rates, which makes private borrowing more expensive.
When nominal interest rates are pinned at an effective lower bound near zero and inflation is low, the usual interest-rate offset weakens or changes character. If fiscal expansion raises expected inflation slightly while the central bank keeps the nominal policy rate unchanged, the expected real interest rate can decline rather than rise. Under those specific conditions, private spending may be crowded in rather than crowded out, lifting the short-run fiscal multiplier above unity—though the exact magnitude remains an empirical battleground depending on openness to trade, debt sustainability concerns, Ricardian equivalence channels, and whether spending is temporary or permanent.
A known empirical fact across advanced economies is that fiscal multiplier estimates vary widely across episodes, countries, and estimation methods, with no single universal number applicable to every recession. An educated hypothesis for why estimates diverge is that multiplier size depends on state-dependent slack, monetary policy reaction functions, and the composition of fiscal measures—such as direct government purchases versus lump-sum transfers—rather than existing as a fixed structural constant.
This creates a bottleneck in fiscal-monetary coordination during deep downturns. If a finance ministry expands spending on the assumption of a large multiplier while the central bank moves aggressively to tighten monetary conditions to curb inflation, higher real interest rates can offset much of the fiscal stimulus. Conversely, when fiscal deficits are large and persistent, concerns over long-run solvency and inflation dynamics can complicate central bank stabilization goals, a tension highlighted in fiscal theory of the price level discussions.
Evaluating Policy Frameworks Under Uncertainty
Practitioners managing portfolios, corporate capital budgets, or public policy portfolios cannot rely on a single point forecast of interest rates or unemployment. Instead, rigorous decision-making maps each policy or strategic move against three core variables:
- Persistence of real frictions: How quickly workers, suppliers, and capital goods can reallocate across sectors after a shock.
- Credibility of nominal anchors: How firmly long-run inflation expectations stay tied to the central bank's target amid supply or fiscal shocks.
- Constraints on policy instruments: Whether nominal rates face a lower bound, balance-sheet limits, or political and institutional friction.
When moving from diagnosis to execution, an analyst or strategist can follow a structured sequence to test any macroeconomic claim:
- Isolate the shock type: Distinguish a real supply or productivity disturbance from a nominal demand or financing disturbance before attributing price and output moves to policy.
- Trace the expectation channel: Identify whether the mechanism requires households or firms to revise multi-year inflation or rate expectations, and check whether historical credibility supports that revision.
- Map the offsetting reaction: Determine how central banks, wage-setters, or fiscal authorities are likely to react over the next four to eight quarters, since their reaction shapes the net effect of any initial impulse.
- Stress-test parameter sensitivity: Re-evaluate the conclusion under slower labor matching, weaker forward-guidance credibility, or tighter financing conditions rather than treating baseline elasticities as exact.
Every analytical framework carries blind spots that practitioners must state upfront rather than masking behind technical jargon. Matching models often simplify wage bargaining and firm entry/exit dynamics, while New Keynesian models can understate financial sector balance-sheet amplification, distributional effects across income groups, or non-linear tail risks during crises. No theoretical model replaces empirical cross-checking against real-time credit spreads, labor market flows, and survey expectations.
Strategic Positioning for Cycle Inflections
Decision-makers navigating rate cycles and labor market shifts should anchor capital allocation and risk limits to real financing conditions, labor reallocation speed, and expectation credibility rather than single headline statistics. When nominal policy rates sit near constraints or inflation expectations test central bank tolerance, businesses and policymakers gain resilience by maintaining balance-sheet flexibility, staging irreversible capital commitments in tranches, and stress-testing plans against both slower-than-expected disinflation and stickier-than-expected labor slack.