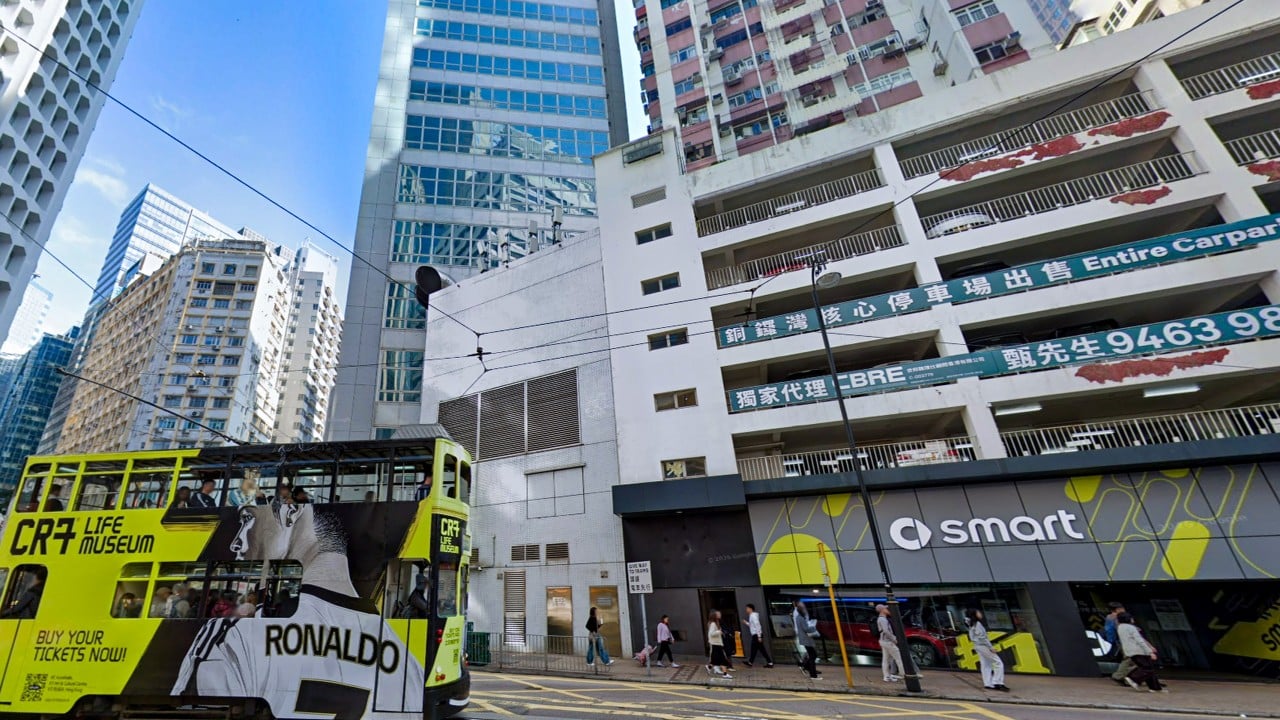
Jardine Matheson’s sale of a long-held Causeway Bay street shop for HK$80 million (roughly US$10.2 million) after more than five decades of ownership is frequently read as a straightforward indictment of Hong Kong retail real estate. That reading confuses corporate capital allocation with sector-wide insolvency. A multi-decade holding exiting at a modest nominal ticket in a high-profile district tells us far more about opportunity cost, conglomerate portfolio pruning, and cap-rate math than it does about a uniform collapse across every storefront in the city.
To understand what the transaction actually reveals, we have to separate three distinct layers of analysis:
- Capital recycling mechanics inside a diversified conglomerate: Jardine Matheson has spent recent periods executing substantial capital recycling, buying back shares, and redeploying balance-sheet liquidity toward higher-return or more strategically aligned assets (such as healthcare imaging and full ownership stakes in core operating arms) rather than sitting on low-yielding legacy real estate.
- The bifurcation of Hong Kong retail property: Street-level retail in prime corridors and enclosed shopping malls do not share the same demand drivers, tenant covenants, or valuation multiples, and foot traffic recovery has not translated evenly into historical peak rents.
- The cost of capital versus rental yield: When borrowing rates stay elevated relative to historical norms and outbound spending habits shift, property owners face a valuation squeeze where nominal asset prices adjust to restore cash-on-cash yields.
Deconstructing the Standard Narrative and Its Blind Spots
Conventional commentary on a single high-street disposition typically follows a predictable chain: a storied conglomerate sells a shop held for generations, therefore high-street retail is broken. That reasoning skips several critical links in the causal chain.
First, a holding period exceeding fifty years means the seller’s historical cost basis is a fraction of today’s valuation, even after cyclical drawdowns. Selling an asset held since the early 1970s is not the same economic event as a leveraged investor dumping a recently acquired shop at a loss. Without knowing the exact acquisition cost, refurbishment outlays, or imputed internal rent charged to operating subsidiaries, a headline sale price cannot prove distress on its own.
Second, a single HK$80 million street shop transaction sits at a very different scale from institutional portfolio trades or prime mall leases. Smaller street shops in Hong Kong often trade to private family offices, owner-occupiers, or local investors who underwrite cash yield, subdivision potential, or long-term land value rather than institutional net operating income growth. Treating a micro-scale disposition as a complete proxy for the entire retail real estate market overstates the signal from one data point.
Third, standard media coverage often treats "retail struggles" as a single monolithic condition. In reality, retail real estate in Hong Kong operates across distinct sub-segments with different tenant mixes, lease structures, and sensitivity to cross-border travel and domestic consumption.
The Portfolio Logic Behind a Legacy Exit
When a diversified holding company sells a long-held commercial unit, the decision sits inside a broader capital allocation framework. Rather than asking "Is this shop worth holding forever?", a disciplined treasury team asks whether the equity tied up in that physical box earns a risk-adjusted return competitive with alternative uses of cash.
Consider the internal cost function of holding a non-core retail unit on a corporate balance sheet:
- Opportunity cost of locked equity: Even without external debt on the specific shop, tying up HK$80 million in a single retail unit carries an implicit hurdle rate equal to what that capital could earn in share buybacks, debt reduction, or operating businesses with stronger compounding prospects.
- Friction and management drag: Single-asset or small-lot retail properties require leasing oversight, maintenance, property taxes, and tenant turnover management that add administrative friction disproportionate to their contribution to a multi-billion-dollar group.
- Strategic alignment: Conglomerates undergoing portfolio simplification routinely shed peripheral real estate holdings that no longer serve an operational footprint or flagship branding purpose, especially when retail formats shift toward experiential spaces or integrated developments.
Educated hypothesis vs. known fact: It is a known fact that Jardine Matheson sold a Causeway Bay street shop held for over 50 years for HK$80 million amid a broader commercial property downturn and ongoing capital recycling initiatives. It is an educated hypothesis—not a confirmed internal memo—that internal hurdle rates and portfolio pruning priorities weighed more heavily on the timing of this specific exit than an inability to find any tenant.
Why Street Shops and Malls Behave Differently
A major flaw in surface-level market commentary is conflating street-level shops with managed shopping centres. In Hong Kong, these two formats respond to different structural pressures.
Street shops rely heavily on pedestrian visibility, frontage width, and immediate footfall along arterial roads or secondary lanes. When consumer spending patterns shift—whether toward outbound travel, online channels, or value-oriented dining and everyday services—street-level tenants face tight gross margins. Food and beverage operators, pharmacies, and personal care retailers often demand shorter leases, rent-free fitting-out periods, or turnover-linked adjustments to survive high operating costs.
Enclosed shopping malls, by contrast, benefit from curated tenant mixes, air-conditioned dwell time, integrated transit links, and centralized marketing. While malls are not immune to softer luxury discretionary spending or shifting tourist habits, institutional landlords can rebalance categories, introduce experiential anchors, and manage anchor-to-specialty ratios in ways a standalone street-shop owner cannot.
There is also a sharp divergence between prime flagship corridors and secondary streets. A shop a few blocks off a main thoroughfare or with awkward floor-plate geometry experiences much wider swings in occupancy and asking rent than a high-visibility corner unit directly linked to major transit flows.
Yield Math, Interest Rates, and Valuation Reset
Commercial real estate pricing comes down to a straightforward relationship between net operating income (NOI) and the capitalization rate (cap rate): property value moves in the same direction as net income and inversely to the required yield.
When interest rates rose from the ultra-low levels of the previous decade, the cost of debt climbed and risk-free benchmarks became more attractive relative to physical property. Even when nominal rents stabilize or recover selectively in specific pockets, buyers demand higher initial yields to compensate for financing costs, leasing uncertainty, and alternative fixed-income or equity returns.
A simple illustration shows the math without inventing market figures. Suppose a street shop generates HK$3.2 million in annual net operating income. At a 3.0% cap rate, its implied valuation is roughly HK$106.7 million. If buyers require a 4.0% cap rate to justify holding the asset against higher financing costs and operational risk, that exact same HK$3.2 million income stream translates into an HK$80.0 million valuation. No collapse in tenant rent is required for the capital value to adjust downward when the required yield expands.
This mechanism explains why capital values can lag or diverge from headline footfall numbers. Tourist arrivals or retail sales volume can show signs of stabilization or growth in specific months, yet buyers still price assets conservatively if net rental growth remains uneven or if financing conditions stay selective.
Structural Shifts Reshaping Tenant Economics
To evaluate where Hong Kong retail property stands, analysts must examine what happens inside the tenant’s profit-and-loss statement rather than looking solely at street crowds.
- Margin compression from non-rent costs: Even where base rents have moderated from historical highs, retailers face elevated labor expenses, imported goods pricing dynamics, and utility or fit-out costs. A lower asking rent does not automatically restore tenant profitability if net sales per square foot are thinner or basket sizes are smaller.
- Changing tourist spending mix: Visitor volume recovery does not automatically replicate past spending patterns. When visitors prioritize experiences, dining, or selective categories over heavy bulk purchasing of luxury or cosmetic goods, tenants calibrated to old spending ratios must adapt their merchandising and store footprints.
- Domestic consumption leakages: Residents traveling outside Hong Kong for leisure, dining, or retail—as well as cross-border shopping habits—create competition for local discretionary wallets, forcing local merchants to compete harder on value and differentiation.
The second limitation of looking only at headline retail sales is that aggregate figures mask category dispersion. Essential services, casual dining, health and wellness, and select specialty formats behave very differently from high-ticket discretionary retail. A landlord’s real risk depends on which category occupies the unit and whether that business model generates enough contribution margin to sustain market rent across lease renewals.
Limitations of Current Market Metrics
Anyone tracking Hong Kong commercial property should treat single-headline metrics with caution. Several measurement traps routinely mislead casual observers:
- Headline prices without yield context: A sale price in isolation tells you nothing about the passing rent, lease expiry profile, or vacancy risk attached to the property at closing.
- Averages across heterogeneous micro-locations: Citywide or district-wide averages blur the gap between prime corner frontages, mid-block units, upper-floor retail, and secondary streets.
- Asking rents versus effective rents: Quoted monthly rents frequently differ from effective net rents once rent-free periods, landlord incentives, and stepped increases are factored in.
- Distressed vs. strategic sales: Not every disposition at a lower multiple reflects forced selling; strategic capital reallocation can produce lower-multiple exits for reasons internal to the seller’s balance sheet.
Acknowledging these limitations does not mean the market lacks real headwinds. Retail landlords still face selective tenant demand, fierce competition for quality covenants, and rigorous underwriting from banks and buyers. It simply means rigorous analysis requires pairing transaction headlines with lease economics and capital structure realities.
Practical Framework for Evaluating Retail Assets
For investors, corporate real estate teams, and analysts assessing Hong Kong street shops or retail portfolios, a disciplined underwriting sequence prevents reactive decision-making:
- Audit true net operating income: Strip out gross figures and calculate net income after property rates, government rent, management fees, insurance, leasing commissions, and realistic vacancy or fit-out allowances.
- Stress-test tenant unit economics: Estimate the tenant’s required sales volume to cover rent plus labor and cost of goods sold, and check whether current footfall and spending habits support that breakeven point.
- Benchmark against alternative capital uses: Compare the unlevered and levered yield against current financing rates, corporate hurdle rates, and other commercial or non-real-estate opportunities.
- Evaluate exit liquidity and buyer pool: Identify who the realistic next buyer is—an owner-occupier, a yield-focused private buyer, or an institutional fund—and underwrite exit cap rates conservatively rather than assuming a return to peak multiples.
This framework has clear boundaries. It cannot predict sudden macroeconomic shocks, shifts in interest rate policy, or abrupt changes in cross-border travel rules. Nor does it replace local on-the-ground inspection of pedestrian flow, building condition, and neighboring tenant stability.
Strategic Play
Treat Jardine Matheson’s Causeway Bay sale as a signal to re-underwrite legacy retail holdings on current yield and capital-efficiency math rather than waiting passively for past peak valuations to return. For property owners, the decisive move is to prune non-core or low-yielding street units where capital is trapped at sub-par returns, redeploy proceeds into higher-returning assets or balance-sheet priorities, and lock in sustainable, margin-viable tenants on remaining core properties rather than holding out for outdated rent benchmarks.